PP139
Depreciation Recapture in Real Estate Syndications
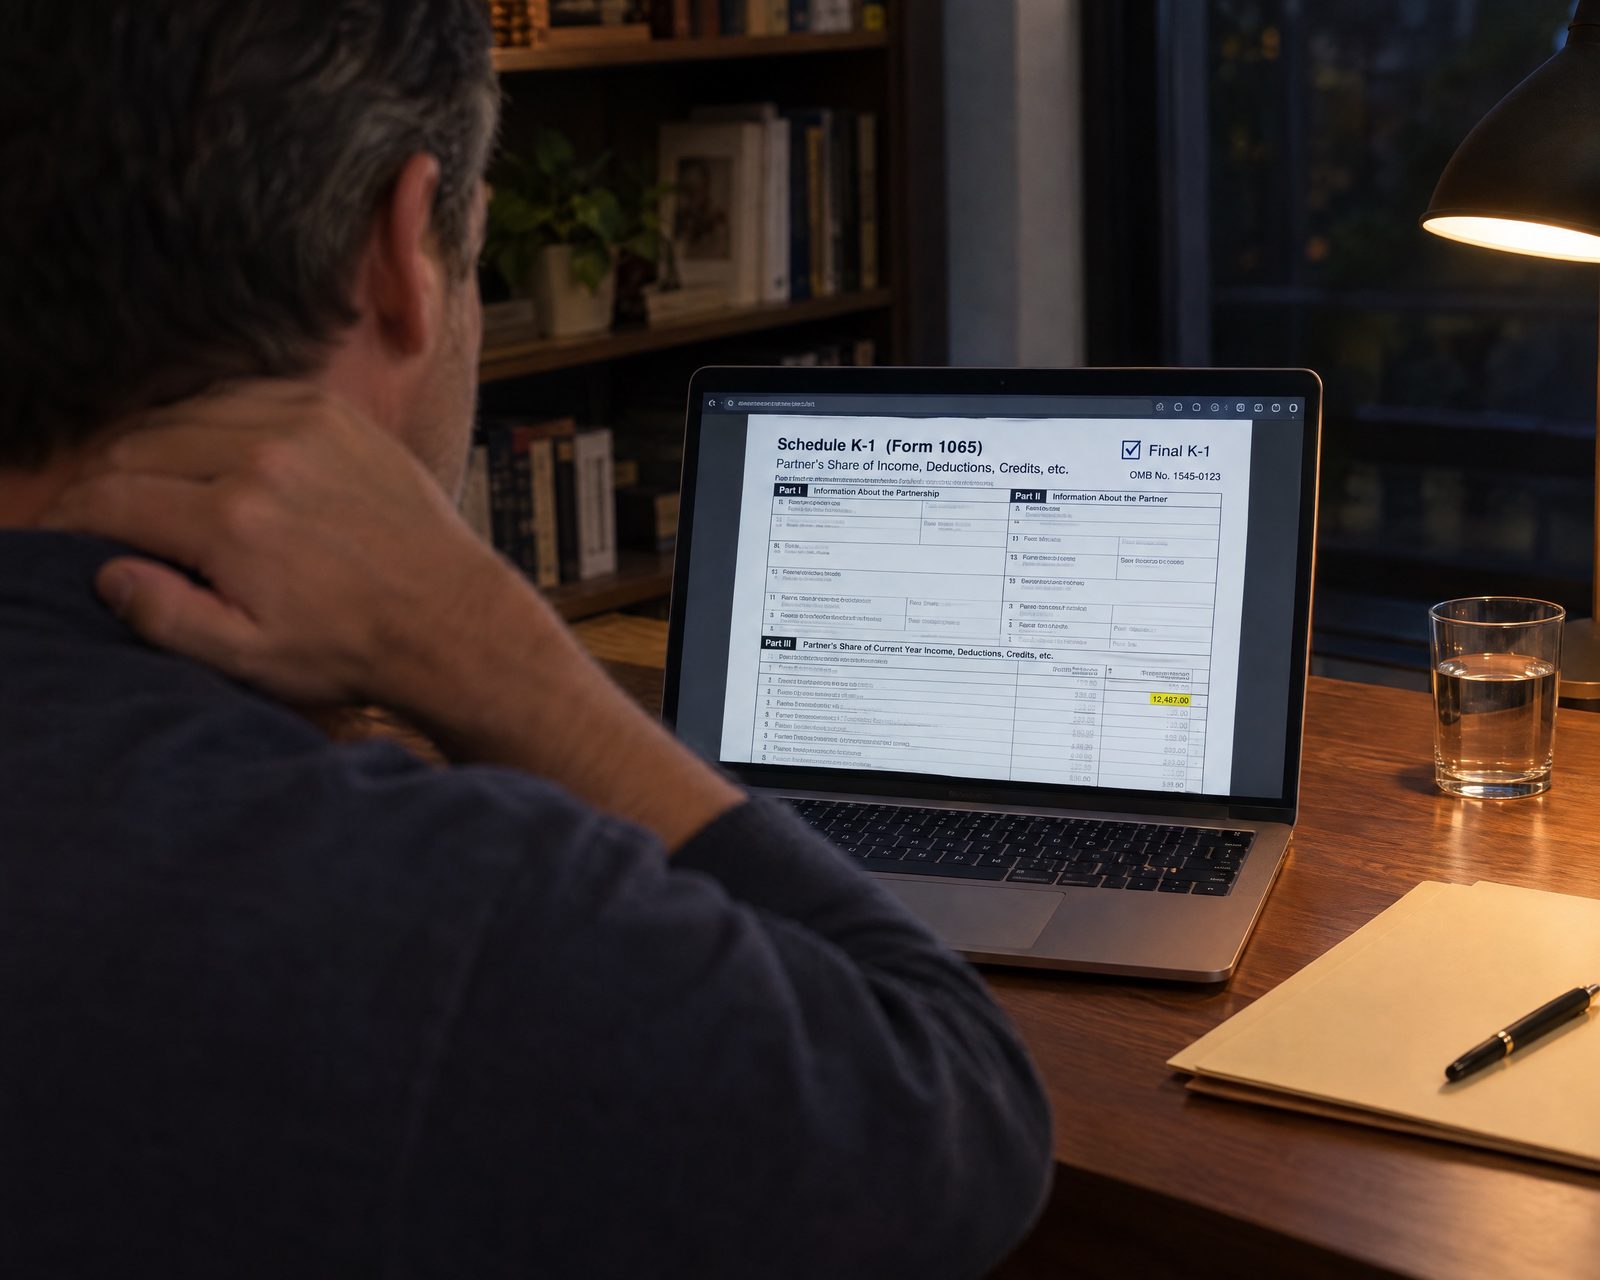
Picture this crazy scenario…
You invest $100K in an apartment syndication. The sponsor does a cost segregation study, uses bonus depreciation, and your first K-1 shows a big loss. You use that paper loss to offset the income from your other deals, and you marvel at how little you owed in taxes that year.
All is right in the investing world. Real estate doing exactly what real estate does best.
But…about 18 months later, the deal goes belly-up, the lender forecloses, and your $100K evaporates into the wind.
And then, as if things couldn’t get worse, you get the deal’s final K-1…and it shows a large taxable GAIN. Even though you lost every dollar you put in.
It sounds impossible, but it actually can happen. (Adam told the full story of an investor it happened to on our podcast.) The cause is depreciation recapture, the evil dark side of bonus depreciation that sponsors rarely mention (and may not even know about).
And while a foreclosure is the extreme version, you’ll run into recapture at the end of almost every deal that uses bonus depreciation and eventually sells for a profit.
Recapture takes back part of your write-off when the deal sells
Depreciation is a tax deduction for tangible things wearing out over time. Often, you take it a little at a time over decades.
Bonus depreciation speeds that up. A cost seg study separates out the parts of a property that wear out faster, like the carpet and appliances in every unit, and bonus depreciation lets you deduct all of that wear in year one. It’s one of the big benefits of real estate investing – you can get a large paper loss up front, even though the deal hasn’t lost money.
But many syndications plan to sell within five to seven years. By then, a lot of that carpet and those appliances are still in use.
So when the property sells, the IRS wants back the deduction you took for wear that didn’t actually happen. That’s depreciation recapture.
To add insult to injury, recapture on bonus depreciation is taxed at the same rates as your salary, which are higher than the normal long-term capital gain rates.
The big implication for LPs is that this additional tax bill effectively reduces your overall return in a deal, sometimes by several points of IRR.
So if a sponsor is pitching bonus depreciation on a deal with a five-to-seven-year hold, I’d ask two questions: have you accounted for recapture, and how much could it affect investors’ returns when the deal sells?
It’s hard to forecast this exactly ahead of time, so if they can’t give you a specific number, that’s not a huge deal – but if their answer shows they haven’t even thought about it, that’s a big red flag.
Whether it stings depends on what you did with the loss
If most of your income comes from a W-2 or a business you own, there’s a good chance you couldn’t use a lot of that year-one loss anyway. Losses from passive syndication investments can generally only offset other passive income, so whatever you can’t use carries forward to future years.
When the deal sells, any year-one loss from that deal you’re still carrying forward gets freed up, and it can offset the gain, recapture included. For a lot of LPs, that can cancel out much of the bill.
The investors who feel recapture most are the ones who already used the loss, whether against passive income from other deals, or against active income through rules like real estate professional status. They got the tax savings up front, so recapture creates a bill, due the year the deal sells.
That’s what happened to the investor in the scenario above. To the IRS, a foreclosure typically counts as a sale, with the loan balance as the sale price.
The early write-offs on a heavily leveraged deal can end up larger than the cash you put in. So in a foreclosure situation, the part of the write-offs beyond your cash comes back as taxable income, even though the deal returned nothing.
Plan for recapture when you take the write-off
Bonus depreciation is still one of the biggest tax advantages of investing in real estate, and I’m not suggesting you avoid it.
But you have to go in eyes wide open, knowing the year-one loss can come with a bill at the end of the deal.
So before you invest, and again before you use the loss, work out with your CPA roughly how big that bill could be. Because by the time the final K-1 arrives, it’s too late to plan for it.
(As always, I’m not a CPA, and I’m certainly not your CPA. How much of this applies to you depends on your full tax picture, so always consult your tax advisor.)
Found this valuable? Join hundreds of sophisticated investors and receive these insights direct to your inbox every week.